- Most lenders offer 4x to 4.5x your income as a starting point, but in 2026 a growing number will go to 5.5x or even 6x for first-time buyers
- A handful of lenders now offer up to 7x income, though this is reserved for very specific circumstances
- 5% deposit mortgages are widely available; some lenders will consider 0% but your credit profile needs to be immaculate
- Government schemes including Shared Ownership, the Mortgage Guarantee Scheme (Freedom to Buy), First Homes, and Deposit Unlock remain open in 2026
- The Bank of England base rate is currently 3.75%, down from its 5.25% peak in 2023 — but market sentiment has shifted in late April 2026, with further cuts now unlikely before 2027. Locking in a competitive rate now matters more than waiting
- The average first-time buyer property in Reading costs around £310,000 (ONS, January 2026)
- With over 40 years of combined experience, David Clift and Helen at Greenstone Mortgages have helped thousands of first-time buyers get on the ladder across Berkshire
The Market Right Now: Why 2026 Still Presents an Opportunity
It has been a turbulent few years for prospective homeowners. From the pandemic-era boom to the interest rate shock of 2022 and 2023, first-time buyers in Reading and across Berkshire have faced a challenging environment. But the picture in 2026 looks noticeably different — and more encouraging.
The Bank of England base rate currently sits at 3.75%, having been held at its March 2026 meeting. That is a significant drop from the 5.25% peak that defined the tighter market of 2023. A leading five-year fixed rate in April 2026 is around 4.35% — meaningfully lower than where buyers stood just two years ago.
Sentiment has shifted in late April 2026. The ongoing conflict in the Middle East has pushed oil prices higher, inflation concerns have resurfaced, and market expectations have moved away from further near-term cuts. Most analysts now believe the base rate is more likely to hold steady than fall through the remainder of 2026, with any meaningful reductions looking increasingly like a 2027 story at the earliest. Some lenders have already begun repricing fixed-rate products upward in anticipation. Waiting for a further rate drop that may not materialise is a risk worth taking seriously.
There is also a broader shift happening on the lender side. Regulators have been reviewing the cap that previously restricted high loan-to-income lending, and in April 2026, the PRA published a consultation proposing to remove the individual firm-level cap entirely. The practical effect is that more lenders are now willing to offer higher income multiples than at any point in recent years — genuinely good news for first-time buyers in this part of the country.
Yes, economic uncertainty remains. Rents in Reading have risen to an average of £1,581 per month (February 2026, ONS) — a 3.7% annual increase. For many people continuing to rent, the financial argument for buying sooner rather than later becomes stronger by the month.
What Is an Income Multiple and Why Does It Matter?
An income multiple — sometimes called a loan-to-income ratio (LTI) — is the figure a lender uses to calculate the maximum loan they are willing to offer you. If a lender offers 4.5x and you earn £45,000 a year, that means a maximum loan of £202,500. It is the first number you need to understand before you begin searching for a property seriously.
For most of the past decade, the majority of UK lenders worked within a range of 4x to 4.5x. That was fine when house prices were lower. The gap between those figures and what a standard income multiple produces means that understanding your full range of options — and knowing which lenders will stretch further — is not just helpful. It can be the difference between buying and not buying.
How Much Can You Actually Borrow in 2026?
Here is where the market has genuinely changed in your favour. Below is a broad guide to how different lenders are positioned right now.
This remains the baseline for most lenders. If you earn £50,000, you are looking at a maximum loan of roughly £200,000 to £225,000 at standard rates.
A growing number of lenders now offer higher multiples specifically for first-time buyers. Nationwide offers up to 6x income through its Helping Hand scheme. Halifax is offering up to 5.5x for qualifying first-time buyers. Barclays has raised its maximum to 6x for borrowers with a combined income of £75,000 or more. NatWest now offers above 6x for applicants earning over £75,000 individually, or joint applicants with a combined income over £100,000. HSBC offers up to 6.5x income for Premier customers.
To put this into perspective: a couple with a combined income of £75,000 borrowing at 6x could access a loan of £450,000. That changes what is realistically buyable in the Reading market considerably.
Some lenders, including April Mortgages and Teachers Building Society (for education sector employees), will go as high as 7x. These are available to a narrower profile of borrowers and come with stricter affordability stress testing. They tend to suit buyers with strong, stable employment and limited existing commitments. Worth exploring with your adviser.
Income multiples are a starting point, not a guarantee. Every lender also runs a full affordability assessment covering your outgoings, existing debts, dependants, and your ability to service the loan if rates were to rise. Two people earning the same salary can receive very different offers. That is why working with an experienced broker matters.
HELEN CLIFT ON INCOME MULTIPLES
Helen Clift — Greenstone Mortgages
Helen Clift explains how Reading buyers can access 6 times income multiples in
2026, including which lenders are open right now, what affects your borrowing ceiling, and
how to position your application for the best outcome.
Deposits: What Are Your Real Options?
The deposit question sits alongside income multiples as one of the two biggest hurdles for first-time buyers. Here is where things stand in 2026.
Widely available — and now permanent
The government-backed Mortgage Guarantee Scheme (Freedom to Buy) was made permanent in July 2025. This matters more than it might seem. Previous iterations had stop-start availability — they opened, closed, and left buyers uncertain. That uncertainty is now gone. Freedom to Buy supports 95% LTV mortgages on properties up to £600,000. For buyers in Reading with a 5% deposit on a £310,000 property, that is £15,500 — a realistic target, particularly when combined with a Lifetime ISA, which adds a 25% government bonus on up to £4,000 saved per year.
More options, better rates
If you are in a position to put down 10%, your range of lenders and available rates increases meaningfully. Products at 90% LTV carry lower rates and face less competition, giving you more choice and often a lower monthly payment. Where possible, building to 10% before applying is worth doing.
Proceed with eyes open
There are lenders who will consider a 0% deposit product, though the eligibility requirements are demanding. Your credit profile needs to be essentially spotless, your income stable, and your financial position strong across the board. From our experience at Greenstone, this route does not work for most buyers and is not always the right option even when technically available. Worth a conversation, but it should not be the plan unless your circumstances firmly support it.
Government Schemes Available to First-Time Buyers in 2026
There is no single replacement for the old Help to Buy equity loan that closed in England in 2023, but in its place there is a broader landscape of support. The key schemes available to first-time buyers in Reading and across Berkshire right now are:
Available permanently since July 2025. This is a meaningful change from the stop-start availability that characterised earlier government deposit support schemes. Buyers can now plan around Freedom to Buy with confidence, knowing it will not be withdrawn before they are ready to proceed. It supports 95% LTV mortgages on homes up to £600,000 and is open to both first-time buyers and home movers.
Buy a share of between 10% and 75% of a property and pay reduced rent on the remainder. Your deposit is 5–10% of your share only, not the full property value. You can increase your ownership over time through staircasing. Household income must be below £80,000 per year. For buyers in Berkshire where prices are higher, this scheme can make an otherwise unaffordable property accessible — and with a much lower mortgage than buying outright.
A government-backed scheme offering properties at between 30% and 50% below market value to eligible first-time buyers and key workers in England. The discount is a permanent covenant on the property, meaning subsequent buyers also benefit from the reduced price. Availability depends on local planning decisions and developer participation.
Both Reading Borough Council and West Berkshire Council operate their own priority lists for First Homes allocations. Key workers — NHS staff, teachers, emergency services — are frequently given priority access to available plots before they open to the general pool of first-time buyers. If you are in one of those roles, you may be closer to the front of the queue than you realise. David and Helen are familiar with the current criteria across both councils and can tell you whether you qualify and how to position your application accordingly.
An industry-backed scheme enabling buyers to purchase a new-build home with a 5% deposit on properties up to £833,250. Unlike the Mortgage Guarantee Scheme, this is available only through participating new-build developers and a limited number of mortgage lenders. If you are looking at new-build properties in Berkshire, this is an option worth exploring.
A developer-subsidised scheme for new-build buyers that reduces the mortgage rate — in some cases to under 1% for an initial period. The lower rate is funded by the developer at the point of sale. Worth understanding properly, as the benefit over a full mortgage term depends on your specific circumstances.
If you have not yet opened one and are between 18 and 39, a LISA should be a priority. Save up to £4,000 per year and the government adds a 25% bonus — up to £1,000 per year — which can be used towards a deposit on a property costing up to £450,000. Two buyers each with a LISA can pool their bonuses towards the same purchase. The account must be open for at least 12 months before the bonus can be used, so starting early matters.
Joint Borrower, Sole Proprietor: Another Route to Consider
If you are struggling to borrow enough on your own income, a Joint Borrower, Sole Proprietor (JBSP) arrangement is worth considering. This allows a family member — typically a parent — to be included on the mortgage for affordability purposes without being named on the property title. Their income counts towards the maximum borrowing, but they have no ownership stake in the property.
It can also be structured to help buyers avoid the additional stamp duty that would otherwise apply if the family member already owned property. This is particularly relevant for buyers in Reading and across Berkshire, where property prices relative to single incomes create a borrowing gap that JBSP can often bridge.
What This Looks Like in Practice: Reading and Berkshire Numbers
To make this tangible, here are worked examples based on current market data. The table below shows the difference between borrowing at a standard 4.5x multiple versus an enhanced 6x multiple — and what that means for buyers at different income levels.
| Income | Standard (4.5x) | Enhanced (6x) | Difference |
|---|---|---|---|
| £45,000 Single buyer | £202,500 | £270,000 | +£67,500 |
| £65,000 Joint buyers | £292,500 | £390,000 | +£97,500 |
| £75,000 Joint buyers | £337,500 | £450,000 | +£112,500 |
Figures are illustrative. Actual lending subject to full affordability assessment and lender criteria.
Against the Reading first-time buyer average of £310,000, a single buyer on £45,000 using a standard multiple falls well short. At 6x, with a 10% deposit of £31,000, the gap closes considerably — and with a scheme like Shared Ownership or First Homes in place, it can close entirely. For joint buyers at £65,000 to £75,000 combined, the enhanced multiples bring a wide range of Berkshire properties into clear reach.
A £310,000 budget currently opens up strong options for two-bed terraces in Tilehurst or Calcot, and modern apartments closer to Reading Station. Buyers targeting Whitley, which sits at the more accessible end of the Reading market, will find that even at standard multiples the numbers start to work with a modest deposit — though enhanced multiples still open up considerably better stock.
By 2026, the Elizabeth Line is fully embedded into how buyers and estate agents price property in Reading. The direct connection into central London has baked a commuter premium into prices across the RG1 to RG6 area that was simply not there five years ago. Reading is no longer competing just with other Thames Valley towns — it is competing with outer London boroughs for the same pool of buyers who want more space for their money. For first-time buyers who live and work locally, that premium is a real headwind. It is one of the key reasons why 5.5x to 6x income multiples are not a luxury in this market — they are often a necessity just to compete for the same stock.
First-Time Buyers in Berkshire: What the Data Says
The numbers from the ONS give us a clear picture of where the market sits locally. The average price paid by first-time buyers in Reading in January 2026 was £310,000. In West Berkshire, first-time buyers paid an average of £316,000. Across Berkshire as a county, the median-income resident in Reading needs approximately 8.3 gross annual salaries to purchase a median-priced property — rising to 11 in Windsor and Maidenhead.
Those ratios underscore precisely why income multiples matter so much in this part of the country. A buyer operating at a standard 4.5x multiple with a £50,000 salary has a loan of £225,000 to work with. The same buyer at 6x has £300,000. In the Reading market, that difference changes what you can realistically buy.
A Word on the Current Economic Context
It would be incomplete to write about the mortgage market in April 2026 without acknowledging what is happening globally. The conflict in the Middle East has pushed oil prices higher and raised fresh concerns about inflation. As a result, market expectations around Bank of England rate cuts have been materially scaled back. The market is no longer pricing in further cuts this year — it is pricing in a hold, and in some scenarios, a potential increase if inflation does not ease. Several lenders have already repriced fixed-rate products upward in response to swap rate movements.
The practical implication for first-time buyers is straightforward: do not wait for rates to fall further before acting. The most likely outcome from current market dynamics is that they stay where they are or move higher in the short term. The further cuts many buyers were hoping for are looking increasingly like a 2027 event, if they come at all. Locking in a competitive deal now — while choice remains broad and lender competition for first-time buyer business is still strong — is the more prudent approach.
Does that mean the market is unfavourable? No. Rates remain well below their 2023 peaks, the regulatory environment is more supportive of higher income multiples than at any point in recent years, and rents in Reading continue to rise — £1,581 per month on average as of February 2026 (ONS). Every month spent renting is a month not building equity. The window is open. The point is simply not to assume it will widen further.
Why Work With Greenstone Mortgages?
That depth of experience matters most in a market like this one, where the difference between a standard lender and the right lender can be tens of thousands of pounds of additional borrowing capacity. Knowing which lenders are currently open to enhanced multiples, which schemes align with your circumstances, and how to structure your application to present your income in its strongest light — that is not something a comparison website tells you.
It also means knowing the local detail that genuinely changes outcomes. Which streets in Tilehurst and Calcot are seeing the strongest demand. How the Elizabeth Line premium is playing out across different postcodes. The specific key worker priority criteria that Reading Borough Council and West Berkshire Council apply to First Homes allocations. That kind of knowledge only comes from years of working in this area day in and day out.
If you are a first-time buyer in Reading or anywhere across Berkshire, the conversation starts with understanding your numbers. Get in touch with David or Helen at Greenstone Mortgages and let us work through what is genuinely possible for you.
First-time buyers hub · Deposit options for first-time buyers
Frequently Asked Questions
Your home may be repossessed if you do not keep up repayments on your mortgage. Greenstone Mortgages is a trading name of WIS Contractor Mortgages Ltd, which is authorised and regulated by the Financial Conduct Authority. Our FCA registration number is 824411. You can verify our registration at register.fca.org.uk. The information contained in this article is for general guidance only and does not constitute financial advice. The information is based on our understanding of current legislation, lender criteria and market conditions as at April 2026, which may be subject to change. Individual circumstances vary and the suitability of any product will depend on your personal situation. Lender criteria, interest rates and scheme availability are subject to change without notice. The income multiple figures and worked examples in this article are illustrative only and do not represent a guarantee of lending. All mortgage applications are subject to status, valuation and lender affordability assessment. Always seek personalised advice from a qualified, FCA-regulated mortgage adviser before making any financial decisions. There may be a fee for mortgage advice. The exact amount will depend upon your circumstances and will be discussed and agreed with you before any advice is given.
Introduction
Navigating the 2026 property market as a first-time buyer can feel like a maze of shifting rates and complex jargon. In this episode of the Greenstone Mortgages podcast, expert adviser Helen Clift breaks down the essentials—from why you might not need a 20% deposit to how a Decision in Principle can, with some lenders, help you secure a rate earlier in your journey. Whether you’re just starting to save or you’re ready to book your first viewing, Helen’s practical, no-nonsense advice will help you move forward with confidence. Watch the full conversation below:

TL;DR – What Helen wants first-time buyers to know
- Plan early and speak to an adviser 6-12 months before you’re ready to buy so you can work on your deposit, credit file and affordability.
- You often don’t need a 10-20% deposit; there are options with smaller deposits, and some specialist 100% products, all subject to criteria.
- Even though fixed rates have risen, property prices and seller expectations have adjusted, so there can still be good opportunities in 2026.
- A Decision in Principle (DIP) first makes you a stronger buyer and, with some lenders, can help you secure a rate while you’re still house-hunting.
- Don’t panic about one or two missed payments – the “six-year myth” is just that. Get your full credit report and let an adviser match you with the right lender.
You can also watch the full conversation with Helen on our YouTube channel here:
Meet Helen from Greenstone Mortgages
Welcome to the Greenstone Mortgages blog. In this episode of our podcast series, we’re joined by Helen Clift from Greenstone Mortgages. Between Helen and David, there’s over 40 years of experience in the financial services sector, and they’ve helped countless clients onto the property ladder. Many of those clients are first-time buyers, who regularly leave reviews praising the support and hand-holding they received throughout the process.
Helen’s journey into mortgages started at a high street bank, where she worked for around 13 years as a customer account manager and then an assistant manager. After a short career break to have children, she returned to financial services in an admin support role for a mortgage adviser, quickly realising she wanted to be back on the advising side. That led her to qualify as a mortgage adviser and eventually join Greenstone Mortgages.
If you’re looking for a location-specific written guide alongside the podcast, you might also like our First Time Buyer Guide in Reading, Berkshire on the Greenstone Mortgages website.
Why first-time buyers gravitate to Helen
Although Greenstone Mortgages works with all types of clients, Helen naturally specialises in first-time buyers. She finds that they often arrive with the same worries: how much deposit they need, whether their credit history is “good enough”, and whether now is the right time to buy.
Looking at her reviews, you can see that first-time buyers in particular value her calm explanations and her willingness to walk them through each step. Many don’t know where to start, and that’s exactly where Helen comes in, offering practical, step-by-step guidance from the first call to getting the keys.
“Nobody teaches you this at school” – why planning ahead matters
One of Helen’s key messages is that first-time buyers should plan ahead instead of waiting until they’ve found a property. She often speaks to clients 6-12 months before they’re actually in a position to make an offer, so they can work on their finances in advance.
In those early conversations, she looks at:
- Your credit record – including any missed payments or existing accounts
- Your current savings and how realistic your deposit target is
- Your income and outgoings, and what that might mean for affordability
- A rough timescale for when you want to buy
With that information, she can set you on the right path. That’s where the line “nobody teaches you this at school” really resonates, Greenstone steps into that gap and becomes the guide you never had in the classroom.
If you want a more detailed written checklist on deposits, schemes and realistic price ranges, you can read our 2026 First-Time Buyer Playbook article on the Greenstone Mortgages site.
Enhanced income multiples and first-time buyer options
In the podcast, Helen explains that more and more lenders now offer higher income multiples to certain borrowers, rather than sticking strictly to the traditional limits. If you fall into the right income and profession brackets and have an appropriate deposit, some lenders may consider higher borrowing levels that can help in higher-priced areas.
These enhanced multiples and various first-time buyer schemes are explored in more depth in our 2026 First-Time Buyer Playbook: Deposits, Schemes and Realistic Price Ranges in Reading. The same principles can often be applied in many parts of the UK, not just Berkshire.
“In terms of deposit, what are lenders looking for these days?”
When asked about deposits, Helen is clear that many clients overestimate what they need. People frequently assume you must have 10% or 20% to be taken seriously, but that’s not always the case. There are lenders who will consider smaller deposits for first-time buyers who pass their checks, and there are also specialist 100% products with strict criteria.
The key points Helen highlights are:
- You don’t automatically need a 10-20% deposit to start a conversation.
- Smaller deposits can work if the rest of your profile is strong.
- A larger deposit usually gives you more product choice and potentially sharper rates.
For a fuller breakdown of deposit levels, different schemes and realistic price brackets, the 2026 First-Time Buyer Playbook article on the Greenstone Mortgages website is a useful companion to this podcast.
Is it still a good time to buy in 2026?
The podcast also addresses a big question Helen hears daily: “With everything going on and rates rising, should I wait or should I buy now?” Recent events have contributed to rate volatility and a cautious mood in the market, so it’s understandable that first-time buyers are unsure.
Helen’s answer is balanced. Yes, fixed rates are higher than they were a few years ago, but property prices and seller expectations have adjusted in many areas. That can mean:
- More realistic pricing and scope to negotiate
- The chance to secure a home that might previously have been out of reach
- Opportunities to benefit if you are prepared and mortgage-ready
With some lenders, you can also secure your rate at Decision in Principle or application stage, which can be valuable while you are still house-hunting. It’s lender-specific rather than guaranteed across the board, and part of Helen’s role is to identify which lenders offer that option for your circumstances.
So rather than trying to “time the market”, Helen encourages first-time buyers to focus on whether the numbers work for them personally and whether the home fits their long-term plans.
The role of the “Bank of Mum and Dad”
When the conversation turns to parental help, Helen confirms that the “Bank of Mum and Dad” continues to play a big role for first-time buyers. Many of her clients use gifted deposits from parents or close family, and many lenders are comfortable with this type of support as long as the paperwork is correct.
Because this topic involves its own rules and lender criteria, Greenstone Mortgages has a separate in-depth article: Bank of Mum and Dad UK 2026 – Greenstone. That piece covers how gifts and loans can be structured, what lenders expect to see, and issues to consider as a family before proceeding.
Fixed vs variable: what’s best for first-time buyers right now?
Another common question is whether first-time buyers should choose a fixed rate or a variable rate in the current climate. Helen’s view, given how quickly fixed rates have been moving, is that many first-time buyers value the stability of a fixed rate.
She often starts by discussing 2-year and 5-year fixed options, and explains how:
- A fixed rate gives you certainty over your monthly payments for the chosen term.
- It can protect you from further base rate increases during that period.
- Some lenders may offer slightly higher maximum borrowing if you choose a 5-year fix, because it is seen as more stable.
The right choice depends on your circumstances: how long you expect to stay in the property, your appetite for risk and whether you think your income will change significantly. These are the kinds of questions Helen works through with each client individually.
Missed payments and the “six-year myth”
One of the biggest myths Helen hears is that if you’ve had one or two missed payments, you have to wait six years before you can even think about a mortgage. She’s very clear: that’s simply not true.
Lenders look at context, not just the headline:
- What type of credit the missed payment was on
- How many payments were missed and how long ago
- Whether the account is now up to date
- What the rest of your profile looks like (deposit, income, other commitments)
That’s why Helen encourages first-time buyers to download their full credit report and review it regularly, rather than assuming they’re “ruined” for years. Tackling this six-year myth head-on not only reassures nervous buyers, it also positions Greenstone as a straight-talking, trustworthy adviser.
Practical tips to look after your credit file
On the podcast, Helen shares simple, practical steps she tells first-time buyers to follow:
- Put essential bills and credit commitments on direct debit to reduce the chance of missing a payment.
- Download your full credit file and review it monthly so you always know where you stand.
- Deal with any errors or unexpected entries promptly, rather than leaving them until just before a mortgage application.
Building these habits gives you a stronger platform when you are ready to apply for a mortgage and helps avoid last-minute surprises.
Do car loans and personal loans affect your mortgage?
Yes, they can. When asked about car loans and personal loans, Helen explains that they may have a real impact on how much you can borrow. During your initial fact-find, she will go through your income, regular outgoings and all existing credit commitments.
Lenders then feed these numbers into their affordability calculators to work out your maximum borrowing. Any loan commitments count as outgoings and reduce the amount that can safely be lent. If you are thinking about buying in the near future, it is sensible to speak to an adviser before taking on a major new loan, especially for a car.
Should you get a Decision in Principle before house-hunting?
Helen always encourages first-time buyers to get their Decision in Principle (DIP) first. With a DIP in place:
- Estate agents and sellers can see you’ve already passed an initial lender check.
- Your offers are taken more seriously because you’ve demonstrated you are proceedable.
- With some lenders, you may be able to secure a rate at DIP or application stage, which has been invaluable while fixed rates have been rising quickly.
Going out viewing without a DIP can lead to disappointment if you later find that the property is outside your borrowing range, so getting this done early can save a lot of stress.
Do you have to use the builder’s or estate agent’s mortgage adviser?
Another myth Helen tackles is that when you buy a new-build, you must use the developer’s recommended mortgage adviser or that you have to use the estate agent’s in-house broker. That’s not the case.
Greenstone Mortgages is a whole-of-market, fee-free broker, which means they can look at a wide range of lenders and products for you. Whether you’re buying a new-build home or a second-hand property, you’re free to choose your own adviser and still benefit from the same level of support.
Why Greenstone Mortgages is well placed to help first-time buyers
Towards the end of the podcast, Helen talks about how she and David are now at the life stage where their own children and their children’s friends – are starting to buy their first homes. That gives them a very personal understanding of how tough it can feel for young buyers in the current market.
First-time buyers working with Greenstone Mortgages can expect:
- Clear explanations from that very first “we’re thinking of buying” chat
- Honest guidance on deposits, schemes, credit issues and realistic price ranges
- Support all the way from Decision in Principle to getting the keys
To dive deeper into specific topics mentioned in this episode, you can explore these related Greenstone articles:
- First Time Buyer Guide in Reading, Berkshire – more location-specific examples and tips
- 2026 First-Time Buyer Playbook: Deposits, Schemes and Realistic Price Ranges – a written roadmap to accompany the podcast
- Bank of Mum and Dad UK 2026 – Greenstone – for families considering gifted deposits or other support
At a Glance
The Bank of Mum and Dad remains one of the most important routes onto the property ladder in 2026.
With rising living costs and affordability pressures, many first-time buyers rely on family support not just for deposits, but also through modern mortgage structures.
Why the Bank of Mum and Dad Is Still So Important in 2026
For many first-time buyers in the UK, getting onto the property ladder has never been straightforward.
In 2026, it has become even more challenging.
With the cost of living increasing and inflation pressures continuing, saving for a deposit is taking longer than expected for many buyers.
We often see clients starting with a 5 percent deposit goal, aiming for 10 percent, but taking years to bridge that gap. During that time, house prices and day-to-day costs can rise, pushing homeownership further out of reach.
This is where the Bank of Mum and Dad continues to play a key role.
How the Bank of Mum and Dad Has Evolved
Traditionally, parents would simply gift a deposit.
Today, the support comes in many different forms.
1. Gifted Deposit (Still the Most Common)
Parents provide part or all of the deposit.
This remains the simplest and most widely used option.
2. Joint Borrower Sole Proprietor (JBSP)
One of the most effective modern solutions.
How it works:
- Parents join the mortgage to support affordability
- They are not on the property deeds
- The property remains solely in the buyer’s name
Key benefits:
- Increased borrowing capacity
- Potentially avoids additional Stamp Duty implications for parents
3. Family Support Through Lender Schemes
Some lenders offer:
- Family-assisted mortgages
- Savings-backed support options
- Offset-style arrangements
While traditional guarantor mortgages have reduced, newer structures still allow parents to support in more flexible ways.
Why This Matters More Now
The Reality in 2026
The outcome is clear:
Without support, many first-time buyers delay purchasing by several years.
What About 0% or 5% Deposit Mortgages?
There are still options available:
- 5 percent deposit mortgages
- Developer incentives
- Lifetime ISA savings
- Limited low or no deposit products
However:
- Affordability checks are stricter
- Interest rates may be higher
- Lender availability can be limited
This is why many buyers still combine these with family support.
Real-World Insight
A typical scenario we see:
A buyer has a 5 percent deposit but struggles with affordability due to income limits.
With a Joint Borrower Sole Proprietor structure, parents support the mortgage.
The result:
- Improved borrowing capacity
- Faster access to the market
- Avoiding years of additional saving
Bank of Mum and Dad: Then vs Now
DID YOU KNOW?
- ✔ A significant proportion of UK first-time buyers rely on family support in some form.
- ✔ Moving from a 5 percent to a 10 percent deposit can take years without assistance.
- ✔ JBSP allows parents to support without being on the property title.
- ✔ Waiting even 1 to 2 years can mean higher property prices and borrowing costs.
Should You Use the Bank of Mum and Dad?
It depends on your situation.
Key considerations:
- Your income and affordability
- Your current deposit
- Your long-term plans
- Your family’s ability to support
The important thing is understanding all available routes, not just the traditional one.
Use Our Mortgage Calculator
Before making a decision, it helps to understand your options clearly.
- Estimate how much you can borrow
- Compare scenarios with and without family support
- Plan your next move with confidence
Why Speak to Greenstone Mortgages
At Greenstone Mortgages, David Clift and Helen Clift bring over 40 years of combined experience in financial services and have helped hundreds of first-time buyers navigate their way onto the property ladder.
We understand:
- How lenders assess affordability in today’s market
- Which structures genuinely work
- How to position applications correctly from the start
If you are unsure where you stand, feel free to get in touch. We are happy to guide you through your options.
FAQs
1. What is the Bank of Mum and Dad?
It refers to financial support from parents, usually through deposits or helping with mortgage affordability.
2. Do parents need to be on the property?
No. With schemes like JBSP, parents can support the mortgage without being on the deeds.
3. Is gifting a deposit the only option?
No. There are now several structured options including affordability support and lender-specific schemes.
4. Are guarantor mortgages still available?
They are less common but have evolved into more flexible modern arrangements.
5. Can I buy without family support?
Yes, but it may take longer depending on affordability and deposit levels.
Compliance Note
Your home may be repossessed if you do not keep up repayments on your mortgage.
Disclaimer
This article is for information only and does not constitute personal mortgage advice. Any recommendation must be based on your individual circumstances and a full assessment of your needs and affordability. Your home may be repossessed if you do not keep up repayments on your mortgage.
TL;DR
In 2026, many first-time buyers in Reading purchase with deposits between 5% and 15%, but the “right” level depends on your situation, property and chosen lender.
Government and lender schemes can help some Reading buyers, but they all come with conditions and risks that need careful explanation before you decide.
Your realistic price range in Reading depends on income, deposit, regular outgoings, and local property prices in the streets and suburbs you’re targeting.
Lenders use their own affordability rules and caps, often linked to income multiples, but these vary and are not guaranteed.
A regulated mortgage adviser who understands the Reading market can help you understand what is affordable and suitable for you, rather than relying on headlines or generic calculators.
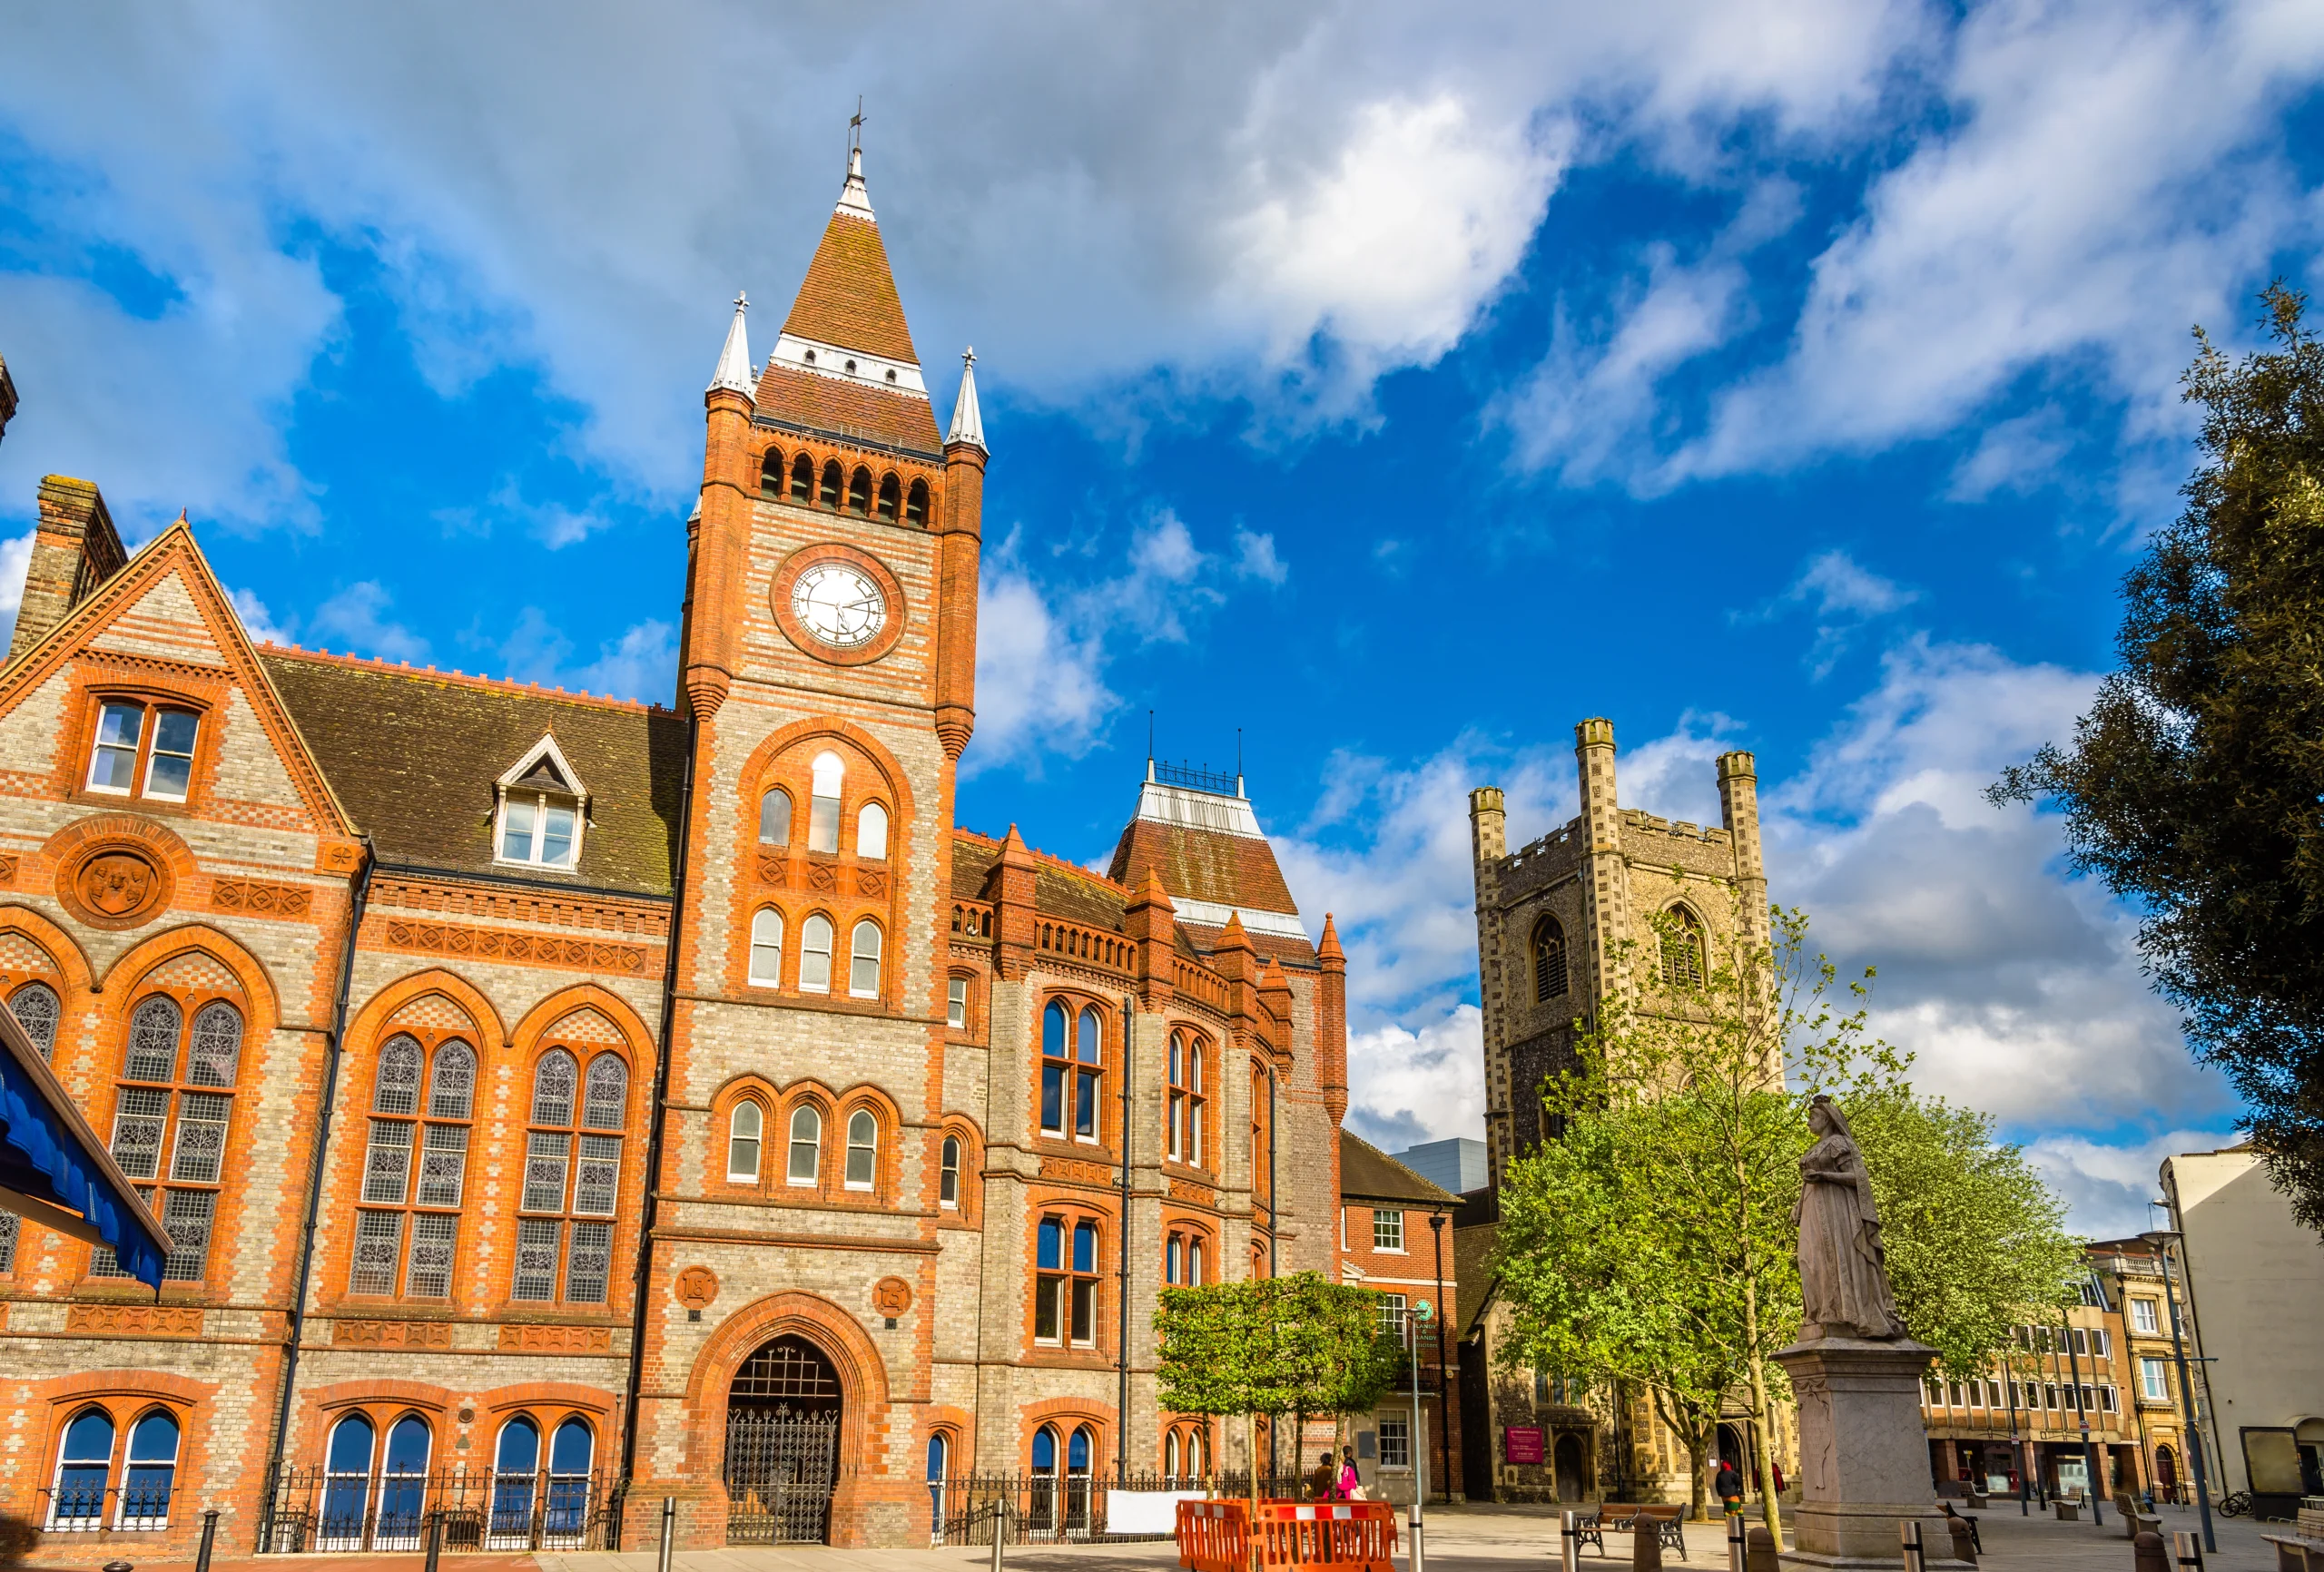
Reading, Berkshire – A vibrant mix of town centre, riverside and suburban living popular with first-time buyers
Buying your first home in Reading in 2026
Reading isn’t just one market; it’s several mini-markets joined together. A two-bed flat near the station or the Oracle feels very different in price and competition to a starter house in Tilehurst or a newer estate near Green Park.
For many first-time buyers we speak to at Greenstone Mortgages, the trade-off looks like this: “Do I buy a flat closer to town and the trains, or do I go a bit further out for a house and more space?” Someone working in London might prioritise walking distance to Reading station, while someone based in Thames Valley Park, Winnersh or Theale may be happier to live further out if it means a garden and a driveway.
At the same time, higher living costs, changing mortgage rates and strong first-time buyer activity mean it’s not always obvious what a realistic first purchase looks like.
Our role is to turn that general picture into numbers and options that make sense for you.
How much deposit do Reading first-time buyers typically use?
Deposit expectations in Reading depend on area and property type – a central flat will be priced differently to a house in Caversham or Woodley. In practice, we often see three broad bands.
Around 5% deposit
This is often the minimum some lenders will consider for first-time buyers, subject to criteria. It is more common on some newer flats or specific developments, though building type and any scheme rules matter. It usually means fewer lender options and can come with higher interest rates than larger deposits.
Example – 5% deposit, central Reading flat:
A client in their late 20s renting in the town centre had saved roughly a 5% deposit and wanted a one-bed flat within walking distance of the station. Their salaries were stable and they had very little debt. For them, a 5% deposit product was a realistic way into the market. The compromise was accepting slightly higher monthly payments than if they had waited for a 10% deposit, because getting out of renting in central Reading sooner was more important to them.
Around 10% deposit
This is a common level for many Reading first-time buyers. It can widen the choice of lenders and sometimes improve the rate compared with 5%, though this is not guaranteed. It may help when you’re competing on popular roads or near good schools or transport links.
Example – 10% deposit, starter house in Tilehurst:
Another couple had been living with family in Caversham and built up a 10% deposit. They were less worried about walking into town and more focused on a two- or three-bed house with parking. That 10% deposit opened up options in parts of Tilehurst and west Reading. By staying flexible on exact streets, we found a home where the repayments fit comfortably within their agreed budget.
15-20%+ deposit
This can sometimes open up more competitive products and may help where there are modest credit issues or more complex income. It is useful if you are stretching to a particular area in Reading where values are higher, such as certain parts of Caversham or riverside pockets.
Example – 15%+ deposit, moving back from London:
We also see buyers coming back from London with 15-20% deposits after years of renting. One buyer wanted a home in Reading they could grow into rather than outgrow in two years. Their larger deposit helped them consider a wider range of properties and gave some lenders more comfort around historical, minor credit issues. The focus here was not “maximum borrowing”, but leaving space in the budget for future childcare and commuting costs.
A larger deposit does not automatically make a mortgage suitable – lenders still need to check that repayments remain affordable for you, even if interest rates change.
Schemes and support options that can affect Reading buyers
Support for first-time buyers changes over time, but some broad types of options frequently come up.
Low-deposit and family-assisted options
Some lenders offer low-deposit products, and there are family-assisted arrangements where relatives in Reading or elsewhere provide additional security or savings. These can help buyers with strong affordability but limited savings.
However, they can create obligations for parents or relatives and may involve additional risks if your circumstances change, so it is important to understand who is responsible for what, and for how long, before proceeding.
Shared ownership or equity-style arrangements
In and around Reading, shared ownership or equity-style arrangements may be available on certain developments. They let you buy a share of a property and pay rent or an equity charge on the rest. This can reduce the initial deposit and purchase price and open up newer homes that might otherwise be out of reach.
You still need to weigh up the total monthly cost (mortgage, rent and service charges), any restrictions, and how easy it will be to staircase or sell later.
Lender and local offers
From time to time, lenders or local initiatives introduce incentives aimed at first-time buyers – for example, help with certain costs or products focused on specific buyer groups. These offers can be useful, but they should not distract from the fundamentals: Is the mortgage affordable, suitable for your situation, and flexible enough for your future plans in Reading?
Working out a realistic price range in Reading
Instead of starting with “What’s the maximum I can borrow?”, it’s often better to ask “What would a comfortable monthly payment look like for me in Reading, after everything else I pay for?”
Income
Lenders will look at your main salary and how secure it is, any bonuses, overtime or commission and how regular they are, and self-employed or contractor income, usually backed by accounts or tax returns. They then apply their own affordability models. Many work with overall caps linked to income (for example, bands around 4-4.5x income for some profiles), but the actual figure can vary between lenders and products and is never guaranteed.
Deposit
In Reading, property prices vary significantly between areas and property types. A higher deposit may help you access more options in more expensive pockets of Reading or reduce the amount you need to borrow. A smaller deposit may limit your choice of lenders and make monthly payments more sensitive to changes in rates and prices. The combination of your deposit and target area (for example, central Reading vs parts of Earley, Woodley, Caversham or Tilehurst) often matters more than the headline percentage alone.
Regular outgoings and credit
Lenders will also consider your existing loans, car finance and credit card balances; essential spending, including dependants, childcare and travel costs (for example, commuting into London, central Reading or local business parks); and past credit behaviour and how you have managed repayments. Even a strong income can be scaled back by high monthly commitments. Sometimes reducing or clearing a particular debt can make a bigger difference to your realistic price range than adding a bit more to your deposit.
Real-world Reading examples
Example – balancing commute and budget:
A couple both working in London had a solid combined income but high rail season-ticket costs. Affordability checks needed to reflect those commuting expenses. When we modelled different scenarios, we found that buying slightly further from the station, but close to a reliable bus route, kept their total monthly cost (mortgage plus travel) within a comfortable range. They decided a slightly longer bus journey was worth it to avoid stretching the mortgage.
Example – reducing debts before buying near the Oracle:
Another buyer wanted a two-bed flat within walking distance of the Oracle. On paper, their income looked strong, but a car loan and credit cards reduced what some lenders were prepared to offer. They spent six months focusing on paying down the car finance and one card. When they returned, the numbers for the type of flat they wanted in Reading looked much more realistic, and they had more options.
These examples are for illustration only – every case is assessed on its own merits.
Getting “Reading-ready” within 90 days
If you want to buy in Reading in 2026, these steps can help you move from “thinking about it” to “offer accepted” in a more controlled way:
- Look at recent sold prices in the specific areas you like (for example, around Oxford Road, Caversham, Earley or Woodley) so your budget is anchored in real local data rather than national averages.
- Map your likely commute (London, Thames Valley Park, Green Park, central Reading) and work out what a realistic travel pattern and cost looks like for you.
- Do a quick “statement check” – if an underwriter looked at three months of your bank statements today, would they see regular income, essential bills and spending that broadly matches what you’ve told us?
- Review short-term borrowing and consider whether reducing it before you apply would put you in a stronger position.
- Gather documents: payslips, bank statements, ID, proof of address and any tax returns or accounts if you’re self-employed.
Talking to a regulated adviser at Greenstone Mortgages early in the process means we can help you prioritise what to do first rather than rushing once you’ve already seen a property you love.
The Greenstone Mortgages team – Local experts helping first-time buyers in Reading find the right mortgage
FAQs – first-time buyers in Reading in 2026
Question 1: Is 2026 a sensible time to buy my first home in Reading?
Answer: There isn’t a single “right year” for everyone. Reading has remained attractive for both buyers and investors, but whether 2026 is sensible for you depends on your income, deposit, job security and plans.
Question 2: How much income do I need to buy in Reading?
Answer: There is no one number because it depends on where in Reading you want to buy, your deposit, and your outgoings. Central flats, riverside homes and popular school catchments will be priced differently from some areas further out. Lenders use their own affordability checks linked to income and expenses, so the amount you can borrow can vary between lenders.
Question 3: Can I afford Reading if I’m currently renting in London?
Answer: Some clients move from renting in London to buying in Reading because they can get more space for a similar or slightly higher monthly outlay once they factor in commuting costs. The exact picture will depend on your rent, deposit, commuting pattern and what type of property you’re aiming for.
Question 4: Is it realistic to buy near Reading station as a first-time buyer?
Answer: It can be, but you may need to compromise on space or property type. Some first-time buyers start with a smaller flat close to the station and later move to a larger property further out once income and equity have grown. Others choose a bigger property slightly further away and accept a longer bus or cycle journey to the station.
Question 5: What if I want a house but can only currently afford a flat?
Answer: Some Reading buyers treat a flat as a stepping stone. For example, a buyer might start with a two-bed flat in east Reading, overpay modestly when they can, and later use built-up equity to move to a house in Woodley. This takes time and planning, but it can mean being on the ladder while working towards a longer-term goal.
Question 6: Can I get a mortgage in Reading if I work in London or remotely?
Answer: Yes. Many Reading buyers commute to London or mix home and office working. Lenders will look at your overall position, including commuting or travel costs and how stable your role is, but where you work does not in itself stop you buying in Reading.
Question 7: When should I speak to Greenstone Mortgages if I want to buy in Reading?
Answer: It often helps to speak to us before you start booking lots of viewings. We can help you understand what may be realistic in the Reading areas you’re considering and suggest any steps to take in advance. We will only recommend a mortgage after a full assessment of your needs, circumstances and affordability in line with FCA requirements.
Greenstone Mortgages is a trading style of WIS Contractor Mortgages Ltd, which is authorised and regulated by the Financial Conduct Authority. This article is based on our understanding of the Reading and wider UK mortgage market as at 2026 and may be subject to change. It is not personalised advice. A mortgage is secured on your home. Your home may be repossessed if you do not keep up repayments on your mortgage.
Market Update
As we move into the final days of March 2026, the UK mortgage market has shifted direction once again.
Over the past week, lenders have begun increasing fixed mortgage rates and withdrawing some of their most competitive products. This change has been driven by movements in financial markets rather than a direct change in the base rate.
For anyone considering a purchase or remortgage, this is an important moment to review your options.
What Has Changed?
Earlier this month, there were signs that mortgage rates were stabilising and potentially heading lower.
However, global economic developments, particularly rising energy prices and renewed geopolitical uncertainty, have altered that outlook.
Swap rates, which influence how lenders price fixed-rate mortgages, have increased by approximately 0.30% in a single week.
Although the Bank of England has kept the base rate at 3.75%, lenders have responded quickly to these market pressures.
Institutions such as Barclays, HSBC and NatWest have:
- Increased fixed mortgage rates
- Withdrawn lower-rate deals
- Adjusted their product ranges
Why Are Fixed Rates Increasing?
It is important to understand that fixed mortgage rates are not set directly by the base rate.
Instead, they are influenced by swap rates, which reflect:
- Expectations around inflation
- Global economic conditions
- Movements in energy markets
When these factors change, mortgage pricing adjusts accordingly.
This is why rates can rise even when the base rate remains unchanged.
Should You Wait or Act Now?
Earlier in the year, many borrowers were choosing to wait in anticipation of falling rates.
In the current market, that approach is less certain.
With lenders adjusting rates quickly and product availability changing frequently, delaying a decision could result in fewer options or higher borrowing costs.
That said, every situation is different, and the right approach will depend on your individual circumstances.
A Different Perspective: Where Opportunities Still Exist
While rising rates naturally attract attention, there is another side to the current market.
Property supply has increased, giving buyers more choice than we have seen in recent years.
This can create opportunities:
- More negotiating power on purchase price
- Reduced competition on certain properties
- Greater flexibility when making offers
In some cases, negotiating a lower purchase price can help offset the impact of a higher interest rate.
The Value of Experience in a Changing Market
In times like these, experience plays a crucial role.
David Clift, who leads Greenstone Mortgages, brings over 25 years of experience in the UK mortgage industry.
Having worked through multiple market cycles, David understands how quickly conditions can change and how important it is to adapt accordingly.
Rather than focusing on short-term movements alone, the emphasis is on helping clients make well-informed decisions that suit their long-term goals.
What Should You Do Next?
If you are planning to buy or remortgage in the coming months, it may be worth:
- Reviewing your current mortgage position
- Exploring available products sooner rather than later
- Understanding how long current rates can be secured for
- Considering both rate options and property negotiation opportunities
A well-timed decision can make a meaningful difference to your overall financial position.
Frequently Asked Questions
Are mortgage rates rising in the UK right now?
Yes. Fixed mortgage rates have increased in late March 2026 due to rising swap rates influenced by global economic factors.
Why are rates rising if the base rate is unchanged?
Fixed rates are driven by swap rates, which respond to inflation expectations and global market conditions rather than just the base rate.
Should I wait for mortgage rates to fall?
Waiting is now less predictable. It is important to review your options based on current market conditions and your individual situation.
Can I still secure a competitive mortgage deal?
Yes. There are still competitive options available, but availability can change quickly, so timing is important.
Summary
The mortgage market has shifted again, and conditions are evolving quickly.
Understanding what is driving these changes and taking timely action can help you stay in control of your options.
Speak to Greenstone Mortgages Today
If you would like tailored advice based on your situation, our team is here to help.
Get in touch with Greenstone Mortgages to discuss your options and plan your next move with confidence.
Your home may be repossessed if you do not keep up repayments on your mortgage.
2026 Mortgage Snapshot
Base Rate: 3.75%
Inflation Range: Around 2-3%
Planning Window: Review your mortgage up to six months early
Local Demand Areas: Caversham, Earley, Woodley
Expert Adviser: David Clift – 25 years in the mortgage industry
The UK mortgage market has experienced significant changes over the past two decades.
At Greenstone Mortgages, founder David Clift has spent more than 25 years helping homeowners and buyers across Reading and Berkshire navigate these changes. During that time, he has advised clients through the 2008 financial crisis, the economic uncertainty following the Ukraine conflict, and the recent cost-of-living pressures that affected households across the UK.
These experiences have reinforced an important lesson.
Economic cycles will always change, but good mortgage advice and careful planning remain constant.
For buyers and homeowners in Reading in 2026, understanding the current market environment can help make better long-term decisions.
Understanding the Mortgage Market in 2026
The mortgage market in 2026 is showing signs of greater stability compared with the sharp interest rate rises seen in previous years.
The base rate set by the Bank of England currently sits at 3.75%, while inflation has moved closer to the 2-3% range.
This has helped ease some of the pressure on mortgage pricing compared with the peaks seen during the cost-of-living crisis.
While some higher loan-to-value mortgage products can still reach around 5% ( Market Average Rates: Many 2 and 5 year fixed deals are currently averaging between 5.01% and 5.09%), many standard fixed-rate deals are now below that level.
However, global factors such as energy prices and geopolitical events continue to influence market expectations.
This means mortgage rates may still move in response to economic developments.
What This Means for Homeowners in Reading
The property market in Reading has remained one of the most active in the South East.
Strong demand continues to come from buyers relocating from London as well as local homeowners moving within the area.
Infrastructure improvements have also strengthened the region’s appeal. With the Elizabeth Line improving travel into central London, areas such as Caversham, Earley, and Woodley have become increasingly attractive to commuters seeking a balance between connectivity and lifestyle.
Because of this continued demand, property values in Reading have remained relatively resilient despite wider economic uncertainty.
For homeowners approaching the end of their mortgage deal, reviewing options early is often beneficial.
Planning Ahead: The Six-Month Window
One of the most valuable tools available to borrowers is the ability to review mortgage options early.
Many lenders allow borrowers to secure a new mortgage deal up to six months before their current rate expires.
This six-month window can provide important flexibility.
By exploring options early, borrowers may be able to:
- secure a favourable rate in advance
- avoid sudden changes in mortgage pricing
- give themselves time to review different lenders and products
This approach has become increasingly common during periods of market uncertainty.
Lessons from 25 Years in the Mortgage Industry
According to David Clift, long-term experience helps provide perspective during uncertain economic periods.
Over the past 25 years he has seen how quickly lending conditions can change.
Major events such as:
- the 2008 financial crisis
- the economic disruption following the Ukraine conflict
- the UK cost-of-living crisis
all created sudden shifts in mortgage affordability and lending policies.
In each case, borrowers who planned early and sought advice were often better positioned than those who waited until the last moment.
Choosing Between a Two Year and Five Year Fixed Rate
Another common question borrowers ask in 2026 is whether to choose a two-year fixed rate or a five-year fixed rate.
A five-year fixed mortgage offers longer certainty, protecting borrowers from future interest rate increases.
However, it also means committing to the current rate for a longer period.
A two-year fixed deal offers more flexibility and allows borrowers to reassess the market sooner.
The right choice depends on several factors including:
- financial circumstances
- future plans for the property
- comfort with interest rate movements
An experienced adviser can help borrowers assess these options.
The Value of Local Mortgage Advice
While national economic trends influence mortgage rates, local market knowledge remains extremely valuable.
A mortgage adviser who understands the Reading and Berkshire property market can help buyers consider factors such as:
- local property values
- lender affordability criteria
- long-term financial planning
Greenstone Mortgages focuses on providing personalised advice tailored to the local property market, helping clients make confident decisions whether they are purchasing their first home or reviewing an existing mortgage.
Final Thoughts
The mortgage market in 2026 is more stable than in recent years, but economic conditions can still change quickly.
Borrowers who seek advice early and review their options carefully are often in the strongest position.
With more than 25 years of experience, David Clift and Greenstone Mortgages continue to help homeowners and buyers across Reading navigate the mortgage process with clarity and confidence.
FAQs
What is the Bank of England base rate in 2026?
The base rate is 3.75% as of March 2026.
When should I review my mortgage?
Review your mortgage six months before your deal ends to explore new options.
Is Reading a strong property market?
Yes. Reading remains popular due to strong commuter links and growing local employment.
Should I choose a two-year or five-year fixed rate?
It depends on your financial goals and risk tolerance.
Compliance
Your home may be repossessed if you do not keep up repayments on your mortgage.
A local investor guide from Greenstone Mortgages
Investing in property remains one of the most effective ways to build long-term wealth. However, the buy to let landscape in 2026 is defined by specific tax thresholds and digital reporting requirements that make expert planning essential.
Whether you are buying your first investment in Reading or scaling a portfolio, this guide covers the 2026 essentials for property success.
Why invest in buy to let property in Reading?
Reading is a Top 5 rental “hotspot” in the South East. Key 2026 drivers include:
- The Elizabeth Line & Station Hill: High-density, high-rent professional demand.
- Tech Corridor: Major employers (Microsoft, Oracle, etc.) providing a stable professional tenant base.
- University Sector: Consistent demand in RG6 for student and research housing.
Rental yields across Reading — 2026 snapshot
| Area | Primary Tenant Profile | Typical 2026 Yield |
|---|---|---|
| RG1 (Town Centre) | Commuters / Young Professionals | 4.6% – 6.2% |
| RG6 (Earley / Uni) | Students / Academic Staff | 5.2% – 5.4% |
| RG30 (West Reading) | Families / Long-term tenants | 4.9% – 5.7% |
| RG4 (Caversham) | High-income professionals | 3.4% (Capital growth focus) |
How much can you borrow? (The 2026 Stress Tests)
Buy to let lending in 2026 relies on Interest Coverage Ratios (ICR). Lenders generally require the rent to cover the mortgage by:
- 125% for basic-rate taxpayers.
- 145% for higher-rate taxpayers.
- Stress Rates: Lenders often calculate this using a hypothetical interest rate of 5.0% to 5.5% to ensure the investment is resilient.
Stamp Duty in 2026 — The “Double Surcharge”
As of 2026, the Stamp Duty (SDLT) surcharge for additional properties in England is 5%. This is added to the standard residential bands which were lowered in 2025.
The 2026 Breakdown for a £300,000 Investment:
- First £125,000: 5% rate = £6,250
- Next £125,000: 7% rate = £8,750
- Final £50,000: 10% rate = £5,000
- Total SDLT Payable: £20,000
Limited Company vs. Personal Name (2026 Update)
The choice of structure is more critical now due to upcoming tax changes:
- Limited Company (SPV): Mortgage interest remains fully deductible. Ideal for higher-rate taxpayers, though mortgage rates are typically 0.5% – 1% higher than personal deals.
- Personal Name: Subject to Section 24, meaning you receive a 20% tax credit on interest rather than a full deduction.
Looking Ahead to 2027: The government has announced that from April 2027, rental income will be taxed at separate, higher rates (22%, 42%, and 47%). Starting your 2026 investment in a Limited Company structure may offer a better “buffer” against these upcoming hikes.
Making Tax Digital (MTD) — April 2026 Deadline
If your total qualifying income (from property and/or self-employment) exceeds £50,000, you are legally required to use Making Tax Digital for Income Tax from 6 April 2026.
- What it means: You must keep digital records and send quarterly updates to HMRC via compliant software.
- Next Step: Landlords with income over £30,000 will join the mandate in April 2027.
Buy to let mortgage rates: Where are we now?
As of February 2026, mortgage rates have stabilized following the Base Rate reductions in late 2025:
- 2-Year Fixed BTL: Typically 4.8% – 5.3%
- 5-Year Fixed BTL: Typically 4.4% – 4.9% (Often used to access better affordability/ICR limits).
Frequently Asked Questions
Is Reading still a good investment in 2026?
Yes. While tax burdens have increased, Reading’s rental demand remains significantly higher than the UK average, helping to offset costs through rising rents.
Can I get a 90% BTL mortgage?
No. Most 2026 lenders require at least a 20% to 25% deposit (75%–80% LTV).
Why use a local mortgage adviser?
Local knowledge is the difference between a 4% yield and a 6% yield. We understand which Reading streets are in high demand and which lenders are currently favoring Berkshire postcodes.
Speak to a Reading buy to let specialist
If you are planning to invest this year, Greenstone Mortgages is here to help you navigate the 2026 tax and lending landscape.
Authors: David Clift & Helen Clift (25+ years experience)
Important notice: Your property may be repossessed if you do not keep up repayments on your mortgage.
Your local roadmap to buying your first home with Greenstone Mortgages
Buying your first home is one of life’s biggest milestones. It’s exciting, but it can also feel uncertain, especially in a fast-moving property market like Reading where well-priced homes can attract strong interest quickly.
Whether you’re considering a flat near Reading station, a starter home in Tilehurst, or somewhere quieter like Woodley or Lower Earley, understanding the process early will help you move forward with clarity and confidence.
At Greenstone Mortgages, based in Reading, we support first time buyers at every stage, helping you understand your options, secure the right mortgage, and navigate the journey smoothly.
Why do first time buyers choose Reading?
Reading continues to be one of the most attractive locations in Berkshire for first time buyers thanks to its strong transport connections, employment opportunities, and long-term growth prospects.
The Elizabeth Line and fast rail services make commuting straightforward, while the Thames Valley continues to attract major employers across technology, finance, and professional services. Combined with good schools, green spaces, and a vibrant town centre, Reading offers a balanced lifestyle for those stepping onto the property ladder.
What are property prices for first time buyers in Reading?
In 2026, the average entry-level property price in Reading ranges from £200,000 for flats to £450,000 for starter homes.
Typical ranges include:
- Flats often start between £200,000 and £300,000
- Starter houses typically range from £300,000 to £450,000
- Popular areas such as Caversham may command higher prices
Understanding local price levels helps you plan realistically and focus your search with confidence.
Which Reading postcodes are popular with first time buyers?
Different parts of Reading offer distinct advantages depending on lifestyle and budget.
RG1 suits town centre living and commuters. RG2 is increasingly popular with professionals and young families, especially near Green Park. RG30 can provide more accessible entry points. RG6 appeals to buyers working near business parks, while RG4 covers the highly sought-after Caversham area.
Choosing the right postcode is about balancing affordability, commute, and lifestyle.
How much can a first-time buyer borrow in Reading?
Lenders assess income, employment stability, credit history, monthly commitments, deposit size, and overall affordability.
While many buyers can borrow around four to four and a half times income, in 2026 we are seeing more “income stretch” products.
Some lenders now offer up to 5.5 times or even 6 times income for first time buyers with strong financial profiles, helping buyers compete in Berkshire’s market.
Having an Agreement in Principle before viewing properties can significantly strengthen your position.
How much deposit does a first time buyer need?
Most lenders require at least a five percent deposit.
For example:
- £300,000 property → £15,000 deposit
- £350,000 property → £17,500 deposit
Stamp Duty in 2026 — key facts for first time buyers
As of April 2025 and continuing through 2026:
- You pay 0% Stamp Duty on properties up to £300,000 (provided the total purchase price does not exceed £500,000)
- You pay 5% on the portion between £300,001 and £500,000
For example, on a £350,000 purchase, the Stamp Duty would be £2,500.
If the purchase price exceeds £500,000, first-time buyer relief typically does not apply and standard Stamp Duty rates may be charged on the full amount.
You should also budget for legal fees, surveys, and moving costs alongside your deposit.
How can you improve your chances of mortgage approval?
Preparing early can make a meaningful difference.
Register on the electoral roll, avoid missed payments, keep debts manageable, and review your credit report. Lenders favour applicants who demonstrate stable financial behaviour.
What mortgage options are available to first time buyers?
There is no single mortgage that suits everyone.
Fixed rates offer payment stability, longer fixes provide certainty, and high loan-to-value products help buyers with smaller deposits. Family support options may also be available.
An adviser can help tailor a solution to your circumstances.
How competitive is the Reading property market?
Competition can be strong, particularly near transport links and major employment areas.
In early 2026, the average time for a well-priced home in Reading to go under offer is around 35 days, making preparation essential.
Having your Agreement in Principle ready before you start viewing is key to competing effectively.
What happens after your offer is accepted?
Once your offer is agreed, your adviser will guide you through the mortgage application, valuation, lender checks, and mortgage offer process.
Your solicitor will handle searches, contracts, and legal work. When everything is complete, you receive the keys to your new home.
What mistakes should first time buyers avoid in Reading?
Common pitfalls include underestimating competition, overlooking commuting costs, delaying mortgage preparation, stretching finances too far, and not planning for interest rate changes.
Being aware of these risks helps you make confident decisions.
What is the Reading property market outlook for 2026?
Reading continues to demonstrate strong demand supported by connectivity and economic growth.
In 2026, we are seeing a shift where more buyers are prioritising RG2 due to its proximity to Green Park business hubs and improved transport links, while demand remains steady across commuter-friendly areas.
As we move through 2026, mortgage rates have shown signs of stabilising, with many two-year fixed rates now sitting around the 4.2% to 4.4% mark, helping to make monthly repayments more manageable compared to recent years.
Limited housing supply and strong employment fundamentals continue to underpin long-term confidence in the local property market.
Why now may be a sensible time to buy
With rates stabilising, lenders offering greater flexibility, and continued demand in Reading, many first time buyers are finding that careful planning can open opportunities that may not have been available previously.
Taking advice early can help you understand what is possible.
Which nearby areas should first time buyers consider?
If you are open to exploring nearby locations, Wokingham, Bracknell, Tilehurst, Woodley, and Lower Earley can offer excellent opportunities depending on your priorities.
A local first time buyer success story
We recently supported a couple working in Reading who had saved a five percent deposit. With careful planning and the right mortgage strategy, they secured a home near Earley and completed within around ten weeks.
Clear guidance helped them feel informed and confident throughout.
First time buyer checklist
- Understand your budget
- Save your deposit
- Check your credit profile
- Obtain an Agreement in Principle
- Begin your property search
- Submit your mortgage application
- Complete your purchase
Frequently Asked Questions — First Time Buyers in Reading
How much deposit do I need to buy my first home in Reading?
Most lenders require at least a 5 percent deposit, although a larger deposit may unlock better rates.
How much can I borrow as a first time buyer in Reading?
Typically around four to four and a half times income, although some lenders offer up to 5.5 or 6 times income for eligible borrowers.
Is Reading a good place to buy in 2026?
Yes, due to strong employment, transport links, and sustained housing demand.
How long does buying a property take?
Most purchases complete within 8 to 12 weeks once an offer is accepted.
Do I need an Agreement in Principle?
Yes, especially given how quickly homes go under offer in Reading.
What additional costs should I budget for?
Legal fees, surveys, mortgage fees if applicable, moving costs, and any Stamp Duty due.
Why choose Greenstone Mortgages?
As a locally based firm, we understand Reading’s property market and the pace at which it moves. We provide access to a wide range of lenders, personalised advice, and support from your first enquiry through to completion.
Our aim is to make your first home journey clear, straightforward, and well supported.
Speak to a Reading mortgage adviser
If you are planning to buy your first home in Reading or the surrounding areas, Greenstone Mortgages would be pleased to support you.
Authors
David Clift and Helen Clift
Mortgage advisers at Greenstone Mortgages with over 25 years of combined experience helping clients secure the right mortgage solutions.
Important notice
Your home may be repossessed if you do not keep up repayments on your mortgage.